In 2020,
Cambodia was one of the countries with the fewest COVID-19 cases. The only
casino in Cambodia’s capital Phnom Penh suspended its operations for 3 months, but
its business recovered shortly after, and outperformed many other casinos in
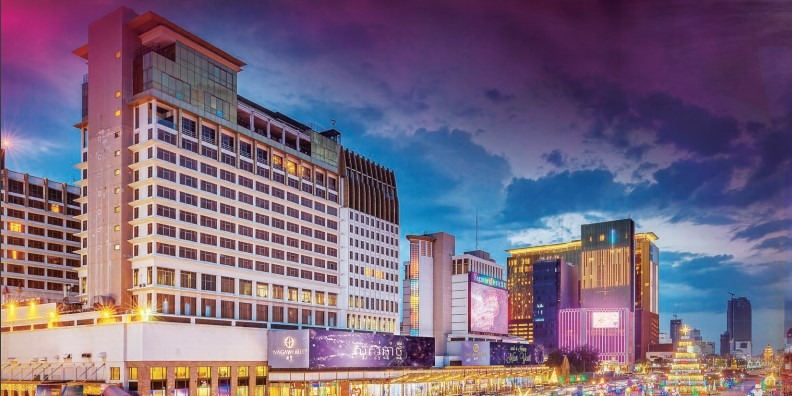
the world. This casino is none other than NagaWorld and we will be examining the
company in this article.
About Nagacorp
Nagacorp Ltd. (“Naga”) had humble beginnings as it started out on a leased barge on the Bassac River near Phnom Penh’s Royal Palace in 1995. In 2003, they moved onshore after NagaWorld completed constructions. Fed up with the banks’ lending rate, founder Tan Sri Dr Chen Lip Keong put up USD 369m of his own money to construct Naga 2. As of 31 Dec 2020, NagaWorld has a total of 512 gaming tables and 1926 electronic gaming machines in operation.
Naga’s operations and activities are mainly located in Cambodia where they are guaranteed to be the only casino within a 200km radius of Phnom Penh until 2045, a key factor that will sustain their earnings. In 1995, the group was awarded a casino license for a period of 70 years and the exclusive right to operate a casino within the designated area until the end of 2045.
The group is constructing Naga 3 in Cambodia, which when completed in 2025 will increase the capacity of the group by at least two times. It is expected that Naga 3 will have 5000 hotel rooms, 1300 gaming tables and 4500 electronic gaming machines upon completion. They are also expanding operations into Russia where they are building a new casino in Vladivostok which will commence operations in 2022.
Tan Sri Dr. Chen Lip Keong is the founder of the group. ChenLipKeong Fund Limited, which is wholly-owned by Dr Chen owns 26.32% of the firm. Dr Chen also owns USD 45m of the NAGACL 7.950% 06Jul2024 Corp (USD) through ChenLipKeong Capital Limited.
Quietly cruising through 2020
While the world was panicking about COVID-19, Cambodia was actually handling it quite well. In The Lancet research report dated 14 Sep 2020, Cambodia was ranked fourth in terms of outstanding efforts on combating against the spread of COVID-19. As of 7 Mar 2021, the total number of confirmed COVID-19 cases was 1,011 with no deaths (although things have changed since then).
Despite the low virus death count, it did not come without costs – its restrictive measures also meant that NagaWorld was closed from 1 Apr 2020 to 8 Jul 2020. For the year of 2020, profit before tax fell by 76.0% YoY to USD 132.1m. The Mass Market segment (the opposite of its VIP business) drove the strong rebound in 2H20, registering an overall recovery rate of about 95% after reopening in July.
In the fourth quarter of 2020, Mass Market Tables’ average daily buy-ins increased by 23% QoQ to USD 3.91m, and even exceeded the corresponding average daily volume recorded in 1Q20. The VIP business also did not fare badly from 8 Jul 2020 to 31 Dec 2020 as it managed to achieve 69% of the average daily volume recorded during the pre-closure period of 1Q20.
Furthermore, Naga pays considerably less in taxes and premiums when compared to other casinos. The revenue from its gaming and hotel operations are exempted from tax and the company only pays monthly obligation payments to the government of Cambodia for the two casino operations. In 2019 and 2020, these payments were only 1.7% and 3.4% of their revenue. On the other hand, for Wynn Macau, their gaming taxes and premiums in 2019 and 2020 were 54.3% and 61.9% of their revenue.
Struck by COVID-19
However, in February this year, there was a stark turnaround in virus case counts and the situation started deteriorating in Cambodia. It was reported that four Chinese travellers bribed at least one security guard and escaped their hotel, avoiding their 14 days of quarantine. Two of them tested positive for COVID-19. Since then, the official number of COVID-19 cases in the country increased by over 30 thousand. As of 13 Jun 2021, the 7-day average of new cases was at 598 although it has seemed to pass its peak.
Subsequently, Naga suspended its business operations on 2 Mar 2021 after incurring an estimated USD 19.7m of monthly expenditures for the first two months of 2021. The company then scaled back hotel and food and beverages operations, retrenched staff and closed facilities to reduce utilities expenditure. After accounting for these measures, the company expects their monthly run-rate operating costs to be at USD 6.6m.
Last year, the company decided to pay all of their 2H20 profits as dividends, amounting to USD 81.7m – which might have been too generous on hindsight as it created an extra burden on their cash balances. While they stated in their 2020 annual report that they value their employees and as such, did not retrench any employees in 2020 during the early virus outbreak, they have since reversed this decision, causing a backlash from the NagaWorld Union.
To cope with its financing costs, they have also retapped and issued another USD200m of the NAGACL 7.950% 06Jul2024 Corp (USD) bonds in early June, and redeemed USD 300m of the NAGACL 9.375% 21May2021 Corp (USD) bonds.
We estimate that the casinos will suspend operations for a longer period this time as the situation is much more severe in Cambodia as compared to in 2020. Thus, in Table 1, we put all these potential scenarios into our consideration and estimate the cash levels in August as if operations were to be suspended for 6 months. According to our projections, cash balances could reach as low as USD 200m in Aug 2021.
Using 2020 as a base reference, current liabilities after deducting for the 2021 bonds amount to USD 168.23m, but these may be offset by trade receivables of USD 119.81m. Thus, the risk that the company may run into liquidity problems seems low.
Table 1: Estimated cash levels by the end of a 6-month suspension in operations
|
USD '000 |
Forecast |
|
Profit from January 2021-February 2021 |
34,959 |
|
Losses from March 2021-May 2021 |
-19,800 |
|
Losses from June 2021-August 2021 |
-23,760 |
|
Total cash outflow for January 2021-August 21 |
-8,601 |
|
Cash and cash equivalents as of December 2020 |
437,741 |
|
Dividends paid |
-81,700 |
|
Remaining cash |
347,440 |
|
Repayment and issuance of bonds |
-100,000 |
|
Estimated cash balance in August 21 |
247,440 |
Source: Company’s statements, iFAST estimates
Other risks
Operating in a frontier market like Cambodia could mean laxer rules and regulations, especially regarding money laundering. However, the country has been strengthening its laws and The National Assembly of Cambodia has adopted two draft laws on anti-money laundering (“AML”) and counter-terrorist financing (“CFT”), and on combating the financing of weapons of mass destruction proliferation.
Naga also engages the services of JB Advisory Services Ltd (“JBAS”) to assess its AML and compliance procedures. In its 2020 annual report, the AML review team is “satisfied NagaWorld maintains full control of the gaming operations and these operations remain compliant with all relevant FATF recommendations.” JBAS also recognised that “NagaWorld remains at the forefront of implementing AML controls in Cambodia” and noted “NagaCorp is committed to full compliance with all national and international laws and regulations on AML.”
Relative valuation
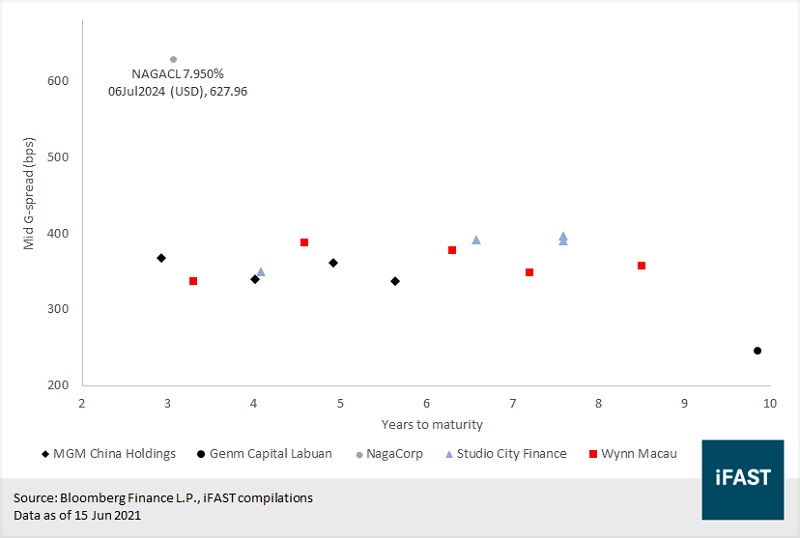
Thanks to Cambodia’s strong handling of the COVID-19 situation in 2020, Naga had the best results among many other casino operators, for example MGM China, Genting Malaysia, Studio City and Wynn Macau. All of its competitors suffered negative earnings before interest and tax (“EBIT”) except for Naga. Wynn Macau and Studio City also registered negative equity as of end-2020. Naga’s credit ratios look the best but the NAGACL 7.950% 06Jul2024 Corp (USD) has the highest bond yield within the sector.
Table 2: Credit ratios of casino operators
|
As of 31 Dec 2020 |
Total debt/ total assets (%) |
Net debt/ equity (%) |
EBIT/interest expense (x) |
|
NagaCorp Ltd |
56.2 |
16.1 |
3.2 |
|
Wynn Macau Ltd |
95.8 |
— |
-1.1 |
|
Studio City Finance Ltd |
38.5 |
— |
-2.8 |
|
MGM China Holdings Ltd |
72.0 |
373.4 |
-3.8 |
|
Genting Malaysia Bhd |
36.2 |
51.19 |
-6.0 |
Source: Bloomberg Finance L.P., iFAST compilations
Bond prices have declined thanks to a retap of the 2024 notes, providing quite an attractive opportunity for bond investors. Operating in a frontier market like Cambodia and the lack of credit facilities could be some of the reasons for its relatively high yield. However, the market seems to have a good appetite for the bonds as shown by the order book amount of over USD 580m in the recent bond offering on 7 Jun 2021, almost thrice of the issuance amount of USD 200m.
Figure 1: Ask yield to maturity for bonds of casino operators 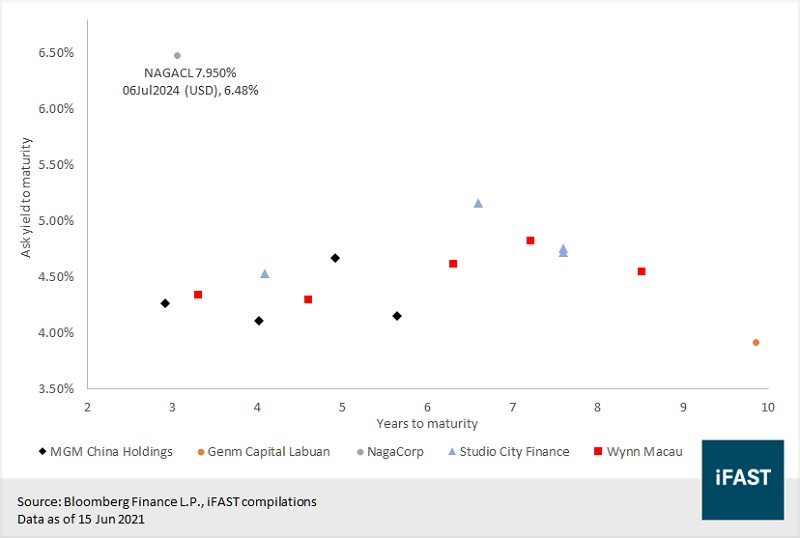
Figure 2: Mid g-spread spread for bonds of casino operators
While the top-line numbers look terrific for Naga, one cannot help but wonder if this level of high revenue growth can be sustainable in the long run. The tax exemptions and low obligation payments could be factors for their performance though. Moreover, the company paid a substantial amount of dividends in 2020. It would be credit negative to bondholders if Naga incurs a higher debt burden and increases dividend payouts - at which point we may turn cautious on the company, but for now, the bonds may be a good investment.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report hold a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!